The Semantic Conflation in Modern Finance
In the contemporary macroeconomic environment of 2026, the boundaries separating disciplined capital allocation from speculative wagering have become increasingly porous. Propelled by the frictionless accessibility of digital brokerage platforms, the mainstream adoption of hyper-volatile digital assets, and the deliberate gamification of retail trading interfaces, market participants frequently conflate two fundamentally distinct financial activities. At the foundation of this widespread confusion is a profound semantic overlap. When analyzing standard lexical definitions, the technical parameters of gambling—typically defined as the wagering of money or something of value on an event with an uncertain outcome, with the primary intent of winning a prize—appear structurally identical to the mechanical act of purchasing a financial security1. Both activities intrinsically demand the presence of three foundational elements: consideration (the initial capital committed, wagered, or deposited), risk (exposure to an uncertain future outcome governed by varying degrees of chance and volatility), and a prize (the expectation of a positive return, yield, or payout)1.
Because both domains strictly require the participant to accept the persistent possibility of capital loss in exchange for a potential future reward, casual retail market participants often fail to distinguish between the respective underlying architectures. However, the economic reality of each system reveals a stark, irreconcilable dichotomy2. Investing, in its most rigorous economic definition, involves the strategic commitment of capital to a productive business endeavor with the mathematical expectation of positive long-term returns, achieved through diligent fundamental research, continuous capital formation, and the systematic diversification of risk3. It represents an acquisition of tangible ownership—a direct stake in real businesses, providing the investor with proportional participation in the ongoing compounding engine of global economic growth, corporate cash flow generation, and human productivity2. The true investor fundamentally operates as an owner, anchoring their expectations in the intrinsic value of the underlying asset1.
Gambling, conversely, involves the deliberate assumption of risk within a mathematically closed system intentionally designed with a negative expected value for the participant1. It is an activity completely dominated by random chance, wherein the inherent risk cannot be systematically mitigated through asset diversification, and the capital committed is not deployed productively into the broader macroeconomic system; it is merely redistributed among participants, minus the substantial friction costs extracted by the operator3. Ultimately, gambling and investing function upon entirely alien logics. While the investor assumes a position of ownership in a cash-producing asset with an expanding horizon, the gambler merely hopes for a favorable, localized variance in a time-bound, binary event2.
Mathematical Architecture: The Primacy of Expected Value
To rigorously separate investing from gambling, the analysis must move beyond the subjective psychological experience of assuming risk and deeply examine the structural mathematical architecture of the underlying activity. The most definitive, objective metric for classifying any form of financial risk-taking is Expected Value (EV). Expected value represents the mathematically anticipated average outcome of a given scenario over an infinite number of trials, calculated strictly as the sum of all possible outcomes multiplied by their respective statistical probabilities5.
The core difference lies in the statistical expectation. When you invest in a diversified portfolio, history suggests a positive return. Conversely, casino games are designed with a built-in house edge. If you study how games like roulette work, you’ll see that while they are designed for entertainment, the mathematical probability always favors the house over the long term.
In the realm of capital markets, expected value is inherently positive over extended durations. By participating in a broad equity index, the investor benefits from the upward drift of economic productivity4. In contrast, closed-loop gaming environments rely on artificially depressed payout ratios relative to actual statistical probabilities, mathematically guaranteeing the eventual depletion of the participant's capital through a mechanism universally known as the house edge6.
The Negative-Sum Reality of the Casino Floor
In casino gaming, the structural parameters are strictly, immutably controlled to enforce a deeply negative expected value for the player. While a participant may experience intense short-term volatility that results in a temporary, exhilarating windfall, the law of large numbers dictates that the continuous repetition of a negative expected value event will inevitably result in total capital destruction1. If a participant were to gamble for an infinite duration, their expected return is mathematically absolute: a 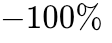 loss of all committed funds1.
The mechanical architecture of American and European roulette serves as the preeminent illustration of how mathematical disadvantage is seamlessly embedded into the entertainment experience. An American roulette wheel consists of 38 individual pockets: the numbers 1 through 36, a single zero (0), and a double zero (00), which are uniquely colored green and placed outside the main red and black betting grid6. A European roulette wheel contains only 37 pockets, omitting the double zero, which statistically alters the house advantage but maintains the negative expected value framework6. Ball deflectors are strategically placed around the interior of the wheel to further randomize the ball's trajectory, ensuring absolute unpredictability on any single, isolated spin6.
The mathematical extraction of wealth occurs through the discrepancy between true probability and casino payout ratios. In American roulette, the true statistical odds of the ball landing in any specific, nominated pocket are exactly 1 in 38, equating to a  chance of success6. If the game were perfectly fair—representing a zero-sum environment with an expected value of precisely zero—a winning "Straight Up" wager on a single number would yield a payout of 37 to 1, perfectly compensating the player for the exact mathematical risk assumed6. However, the casino payout for a successful single-number wager is strictly capped at 35 to 16.
This artificial deflation of the payout ratio relative to the true underlying probability is the engine of the house edge. Furthermore, the inclusion of the green 0 and 00 spaces ensures that all even-money "outside bets"—such as wagers on Red/Black, Odd/Even, or High/Low (1-18 or 19-36)—are automatically surrendered to the house when the ball lands on green, effectively nullifying the illusion of a 50/50 proposition6.
To fully understand the vast array of localized risk propositions within this negative-sum ecosystem, one must categorize the various wagers available to the participant.
|
Bet Type Classification |
Specific Wager Name |
Description of the Covered Outcome |
Payout Ratio |
Implied Volatility |
|
Inside Bet |
Straight Up |
A wager on one single specific number on the grid. |
35:1 |
Extreme |
|
Inside Bet |
Split Bet |
A wager on the dividing line between two adjoining numbers. |
17:1 |
Very High |
|
Inside Bet |
Street Bet |
A wager on an entire row of three consecutive numbers. |
11:1 |
High |
|
Inside Bet |
Corner / Square |
A wager on a cluster of four adjoining intersecting numbers. |
8:1 |
High |
|
Inside Bet |
Five-Number (The Monster) |
A wager covering strictly 0, 00, 1, 2, and 3. |
6:1 |
Moderate-High |
|
Inside Bet |
Sixline |
A wager covering two adjoining rows of three numbers. |
5:1 |
Moderate-High |
|
Outside Bet |
Column Bet |
A wager on an entire vertical column of 12 numbers. |
2:1 |
Moderate |
|
Outside Bet |
Dozens Bet |
A wager on numerical blocks of 12 (1-12, 13-24, or 25-36). |
2:1 |
Moderate |
|
Outside Bet |
Odd / Even |
A wager on the numerical parity of the winning pocket. |
1:1 |
Low |
|
Outside Bet |
High / Low |
A wager on the ball landing in 1-18 or 19-36. |
1:1 |
Low |
|
Outside Bet |
Red / Black |
A wager on the specific color of the winning pocket. |
1:1 |
Low |
Data regarding roulette mechanics, table layout, and standard payout ratios.
[cite: 6]
Through these subtle structural mechanisms, the game functions flawlessly as a mechanism for wealth consumption. The same immutable logic applies to state-sponsored lotteries. A rigorous mathematical analysis of the French Loto, for instance, demonstrates that because the probability of success is infinitely small compared to the magnitude of the payout, every single ticket purchased actively destroys approximately €0.89 of real wealth by mathematical certainty5. Over a lifetime of participation, the lottery guarantees an expectation of €4,800 in destroyed personal wealth for the average participant5. The only scenario in which lottery expected value becomes marginally positive is during anomalous, extreme jackpots (e.g., above €25 million), but capitalizing on this requires an infinite bankroll and infinite time, making it a functional impossibility for the retail participant5.
The Positive-Sum Dynamics of Capital Markets
In stark contrast to the rigidly fixed prize tiers and discrete probabilities of casino games or lotteries, broad capital market investing utilizes continuous probability5. The financial market features a near-infinite set of possible return distributions, tethered fundamentally to the expansion of human productivity, corporate innovation, and compounding cash flows1. When an individual purchases shares in a broadly diversified equity index, they are acquiring fractional ownership in the future revenues of hundreds or thousands of enterprises globally1. As these collective entities innovate, produce tangible goods, and generate quarterly profits, the aggregate value of the market system increases, directly rewarding the participant4.
The expected value equation for continuous long-term investing, though subject to severe short-term macroeconomic volatility, relies on a historical, annualized return rate5. The formula for expected value in this continuous environment can be expressed as:
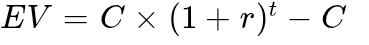
Where  represents the initial capital committed,
 represents the annualized rate of return (historically averaging near
 for major global indices), and
 represents the time horizon in years5.
Utilizing this continuous mathematical framework, historical data demonstrates that holding a highly diversified global index for a period of 10 years yields a positive absolute return  of the time5. Over a 30-year long-term investment horizon, the mathematical probability of suffering a total,
 capital loss in a diversified vehicle (such as an MSCI World Exchange-Traded Fund) is conservatively and historically near zero5. When juxtaposed against the guaranteed wealth destruction of the lottery, average lifetime investing in broad global markets generates a mathematical expectation of
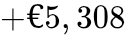 in pure profit5.
This statistical reality highlights a profound, structural inversion between the two domains. In a casino environment, the longer a participant remains at the table and continues to expose capital to the house edge, the higher the mathematical certainty that they will lose their entire bankroll5. In the financial markets, the longer an investor remains consistently invested, the narrower the statistical variance in their annualized returns becomes, and the more predictably those absolute returns converge upon the highly positive long-term market average1.
The Fallacy of Systematized Wagers in Closed Loops
The profound psychological difference between a gambler's mindset and an investor's mindset is most starkly illuminated by how each approaches strategy, variance, and system design. In the realm of negative expected value games, participants frequently attempt to overlay highly complex betting systems onto purely random, independent events in a desperate effort to artificially engineer long-term profitability6.
The digital era has seen a resurgence in the popularity of these progressive betting strategies, fueled by online forums and gamified platform features that track historical spin data to identify illusory "trends"6. Players mistakenly believe that consecutive strings of colors, or the recent frequency of green numbers, dictate future outcomes, directly violating the mathematical principle of independent probability6. To combat the house edge, players deploy an array of historical progression strategies, originally formulated centuries ago, directly onto the roulette table.
|
Strategy Name |
Core Methodology |
Functional Mechanics |
Inherent Risk Profile |
|
The Martingale |
Loss Recovery |
The player doubles their wager size immediately after every loss on an even-money bet (Red/Black). A single subsequent win recovers all prior losses plus one original unit of profit. |
Extremely High. Exponential bet scaling quickly leads to total bankroll destruction or hitting table limits during prolonged losing streaks. |
|
The D'Alembert |
Bankroll Management |
The player selects a baseline unit. They raise their wager by exactly one unit after a loss, and lower it by exactly one unit after a win. |
Low to Moderate. It prevents extreme, exponential losses but generates minimal upside. |
|
The Reverse D'Alembert |
Momentum Riding |
The inverse of standard D'Alembert: the player raises the wager by one unit after a win, and lowers it by one unit after a loss. |
Low to Moderate. Attempts to capitalize on winning streaks while mitigating rapid drawdowns. |
|
The Paroli (Reverse Martingale) |
Streak Capitalization |
The player aims for three consecutive wins. The bet remains flat after a loss but is doubled after a win. If a sequence of three is hit, the player reverts to the baseline unit. |
High. A prolonged absence of winning streaks will slowly but methodically drain the player's bankroll. |
|
The Fibonacci Sequence |
Mathematical Progression |
Wagers follow the Fibonacci mathematical sequence (1, 1, 2, 3, 5, 8, 13…). Wager sizes are increased according to the sequence following a loss. |
High. While slower to scale than the Martingale, a deep losing streak will force unsustainably large wagers. |
|
The Labouchère (Cancellation) |
Targeted Goal Attainment |
The player divides a target profit into a random sequence of numbers. They bet the sum of the first and last numbers. Wins result in crossing numbers off; losses require adding the lost sum to the end of the sequence. |
Moderate to High. It creates a psychological illusion of manageable progression but can balloon into massive required wagers if a losing streak expands the sequence. |
Analysis of progressive wagering strategies deployed in negative EV environments.
[cite: 6]
While these progression systems temporarily alter the short-term variance and volatility trajectory of the participant's bankroll—sometimes providing a string of minor, satisfying victories—they all suffer from a fatal, inescapable mathematical flaw: they absolutely do not alter the foundational expected value of the underlying game6. Because each spin of the wheel is a strictly independent event containing a mathematically embedded house advantage, no arbitrary sequencing of wagers, no matter how elegant or complex, can magically transform a negative expected value into a positive one6. The strategies merely act as variance reallocation tools. In systems like the Martingale, the player trades a high probability of making a tiny profit for a microscopic probability of suffering a catastrophic, total ruin event6. Eventually, the player will encounter a localized losing streak of sufficient length to either exhaust their capital entirely or collide with the casino's maximum betting limit, resulting in devastating loss.
In sharp contrast, the strategies utilized in long-term capital investing are inextricably linked to the fundamental realities of asset pricing, intrinsic value, and capital accumulation. Strategies such as dollar-cost averaging—the consistent investment of fixed capital amounts at regular intervals regardless of asset price—and portfolio rebalancing do not seek to magically predict random short-term market fluctuations. Instead, they are meticulously designed to efficiently capture the naturally positive expected value of the broader market over time, simultaneously mitigating the severe emotional pitfalls associated with attempting to time market tops and bottoms1. True investing strategy is characterized by slow, steady, and boring consistency, whereas gambling strategy is characterized by aggressive, high-risk maneuvers hyper-focused on isolated, rapid-resolution events2.
Time Horizons and the Liquidity of Risk
The temporal dimension is a critical factor in differentiating a fundamentally sound investment from a highly speculative gamble. Sound investing necessitates an expansive time horizon typically measured in years, if not decades1. The modern financial participant is continuously bombarded with high-frequency short-term noise—daily price fluctuations, algorithmic flash crashes, quarterly earnings surprises, and geopolitical macroeconomic shocks. However, the disciplined investor purposefully ignores this short-term volatility to aggressively latch onto the long-term upward macroeconomic trend4.
Gambling is inherently characterized by a hyper-compressed, instantaneous time horizon. The gambler focuses exclusively on an isolated, rapid-resolution event: a single spin of the roulette wheel, the final whistle of a sporting match, or the Friday expiration of a derivative contract1. When an individual enters a casino, their time horizon is functionally microscopic. Nobody approaches a roulette table expecting to wager continuously for months or years; they operate with the expectation of getting lucky quickly and securing a rapid windfall before the mathematical reality of the house edge sets in1. They are not participating in an ongoing enterprise; they are wagering on a binary outcome, walking away with either a payout or an absolute zero2.
This temporal distinction profoundly impacts the participant's structural ability to manage and mitigate risk. One of the paramount systemic advantages of investing is the capacity to diversify across a wide spectrum of asset classes—domestic equities, emerging markets, fixed income, real estate, and commodities—thereby spreading risk and severely dampening aggregate portfolio volatility3. Furthermore, robust capital markets provide continuous liquidity, allowing an investor to exit a position, implement trailing stop-loss strategies, or adjust their overall portfolio weightings in response to shifting fundamental corporate data, thus actively preventing total capital destruction3.
In a traditional gambling scenario, risk mitigation of this sophisticated nature is structurally impossible. A gambler throws their entire allocated capital into a singular pot, tethered to a binary event, completely devoid of a loss mitigation strategy3. Once a roulette bet is placed on the felt and the croupier announces "no more bets," the participant cannot liquidate a portion of their wager mid-spin to preserve capital6. The absolute lack of underlying tangible ownership means the capital is entirely surrendered to the predetermined, rigid mathematics of the game3.
The Gamification of Capital Markets in 2026
Despite these clear structural, mathematical, and temporal boundaries, the behavioral lines between investing and gambling have blurred significantly in the post-pandemic era, culminating in the complex market environment of 2026. This era is characterized by highly accessible, zero-commission digital brokerage applications that have successfully merged the user interface of interactive mobile entertainment with the underlying infrastructure of global capital markets. This systemic phenomenon, widely studied as the gamification of retail trading, has fundamentally altered how a new generation of market participants interacts with financial assets8.
The Illusion of Gamified Success
Digital brokers have aggressively deployed "hedonic" gamification techniques—such as digital confetti drops upon trade execution, sophisticated points systems, social leaderboards, copy-trading functions, and variable lottery-style rewards for deposits. These behavioral nudges were previously the exclusive domain of mobile video gaming and digital casino applications8.
Extensive regulatory research clearly demonstrates the behavioral impact of these architectural platform changes. The Ontario Securities Commission (OSC) conducted empirical research revealing that simply providing retail investors with digital "points" possessing strictly negligible economic value for executing buy or sell orders successfully increased participants' trading frequency by almost 40%8. When the act of investing is structurally presented through the stylistic lens of a fast-paced game, it profoundly obfuscates the reality that the platform is facilitating serious, capital-risking financial transactions2.
Participants who naturally gravitate toward these highly gamified, hedonic trading interfaces tend to exhibit excessively noisy, highly irrational trading strategies, actively attempting to time market tops and bottoms rather than adhering to disciplined methodologies10. Conversely, participants who favor non-gamified, traditional institutional platforms display stronger contrarian behavior and a higher adherence to long-term valuation metrics10.
The Rise of 0DTE Options and Speculative Asset Classes
This shift in platform architecture has perfectly coincided with the explosive retail popularity of high-risk, speculative financial instruments. The historic "meme stock" mania surrounding companies like GameStop violently illustrated how localized social sentiment, coordinated retail trading via online forums, and gamified access could totally detach a company's stock price from its fundamental economic reality9.
Furthermore, the proliferation of Zero Days to Expiration (0DTE) options has allowed retail participants to wager directly on the intraday price movements of major macroeconomic indices with massive, asymmetrical leverage. These derivative instruments expire on the exact same day they are traded, compressing the financial time horizon from decades into a matter of mere hours or minutes. At this microscopic timescale, the directional movement of a financial asset ceases entirely to be driven by macroeconomic fundamentals, forward guidance, or corporate value creation; it operates much closer to a mathematical random walk12. Consequently, trading highly leveraged 0DTE options begins to mathematically and behaviorally mirror placing a wager on a roulette wheel, moving the activity from the realm of investment strictly into the realm of gambling9.
Demographic data strongly correlates these activities. Retail participants belonging to Generation Z who identify as frequent gamblers are statistically much more likely than non-gamblers to be heavily invested in highly speculative digital assets such as cryptocurrencies, non-fungible tokens (NFTs), and complex derivatives7. These younger cohorts are also significantly more likely to invest on margin—utilizing borrowed money to finance leveraged positions, amplifying both their potential upside and their risk of total ruin7. These instruments are widely acknowledged by industry professionals as exceptionally high-risk, predictably resulting in severe underperformance relative to broadly diversified, less volatile long-term index investments7.
Psychological Drivers of Misallocation
If rigorous mathematics clearly dictate that long-term, diversified investing is the vastly superior strategy for wealth accumulation, one must deeply question why a massive, growing segment of the retail market consistently opts for negative expected value scenarios. The answer does not lie in a lack of available data, but rather in behavioral finance and the deeply ingrained psychological biases that govern human decision-making under conditions of uncertainty.
The Allure of the Long Tail and Positively Skewed Returns
Human cognition is notoriously poor at intuitively grasping probabilities, particularly at the extreme margins of statistical distributions. In fundamentally sound investing, the probable outcomes are typically clustered tightly around a slightly positive median4. For example, the historical annual return distribution of the S&P 500 Index roughly resembles a normal, bell-shaped distribution centered around a slightly positive median return4. This means an investor can expect a relatively steady, albeit unspectacular, compounding of wealth over time. The outcomes are highly predictable over a long enough time horizon, lacking the thrill of extreme variance.
Gambling and highly speculative single-asset trading, however, rely heavily on positively skewed expected return distributions4. This statistical phenomenon, often referred to in quantitative finance as a "long tail," describes a highly asymmetric environment where there is a massive, overwhelming probability of realizing a complete capital loss, offset only by a microscopic probability of achieving a colossal, life-altering windfall4. The human brain is disproportionately seduced by the sheer magnitude of the potential prize. Evolutionary psychology suggests humans prioritize the low-probability dream of sudden, transformative wealth over the mathematical certainty of gradual capital erosion4. Aiming for the average return of the aggregate marketplace is mathematically sound but emotionally unfulfilling for a participant seeking an immediate socio-economic paradigm shift4.
The Illusion of Control
Another devastating psychological trap is the "illusion of control"—the cognitive bias wherein individuals falsely believe their personal skill, intellect, or proprietary strategy can influence or accurately predict an outcome that is predominantly governed by random chance12. On a single-day timescale, predicting a specific stock's directional movement is essentially a random exercise12. However, day traders, option speculators, and meme-stock enthusiasts often falsely attribute random short-term success to their own analytical prowess, deeply encouraging them to increase their subsequent wager sizes and trading frequencies12.
This exact illusion is equally prevalent, and equally destructive, on the casino floor. DraftKings and other modern operators frequently provide players with historical tracking boards—digital displays showcasing the history of past spins, the frequency of red or black numbers, or the occurrence of green zeroes6. Despite the immutable mathematical fact that each spin is a perfectly independent event totally unaffected by the spin that preceded it, players utilize this irrelevant data to adjust their wagers, falsely believing they are identifying actionable "trends"3. This manufactured illusion of strategic depth keeps the participant engaged in a game they are mathematically guaranteed to lose.
The Neurology of Intermittent Rewards
Both casino gambling and high-frequency speculative trading hijack the brain's dopamine pathways through a psychological mechanism known as random intermittent reinforcement4. When a behavioral reward (such as a casino payout or a massively profitable options trade) is delivered on a highly unpredictable, variable-ratio schedule, it creates an immensely powerful, deeply entrenched behavioral reinforcement loop. This is the precise neurological mechanism that drives the extreme addictiveness of slot machines, and it is identically triggered when a retail trader obsessively checks a gamified brokerage app to see a highly volatile portfolio randomly spiking in digital value4.
For many active market participants, the primary motivation to trade is not grounded in a rational, calculated desire to build generational wealth, but rather in a subconscious compulsion to experience the physiological thrill of the wager itself. Such individuals essentially use the financial markets as a socially acceptable, highly accessible substitute for traditional casinos, lotteries, or sportsbooks7. Compulsive traders, much like pathological gamblers, derive a visceral, neurological excitement simply from the sheer act of risking capital. Disturbingly, neurological studies suggest that severely addicted participants can even receive a perverse dopamine rush from the act of losing, as the brain becomes addicted to the tension of the outcome rather than the financial result7. Consequently, breaking a compulsive day-trading habit can be as psychologically demanding and clinically difficult as recovering from a severe, long-term gambling addiction7.
Furthermore, macroeconomic stress acts as a catalyst for this behavior. A comprehensive study conducted in 2018 found that risk-seeking investors actually chose to exit stock trading and return to conventional, high-risk gambling activities following periods of intense stock market volatility, indicating that when financial markets become highly chaotic, the fixed parameters of actual gambling begin to look like a psychologically "safer" bet to the addicted mind7.
Mapping Assets on the Spectrum of Risk
Given the extreme complexities of the 2026 market, it is highly inaccurate to view investing and gambling as a rigid, binary classification. Instead, they occupy the extreme, opposing poles of a continuous, highly nuanced spectrum of risk, chance, and expected return1. The specific placement of any financial activity on this spectrum depends entirely upon the designated time horizon, the mathematical degree of diversification, the underlying intrinsic cash-flow value of the asset, and the participant's core behavioral intent.
|
Asset / Financial Activity |
Fundamental Nature |
Average Time Horizon |
Expected Value (EV) |
Role of Chance vs. Fundamental Value |
|
Money Market / Treasuries |
Ultra-Conservative Investing |
Very Short to Long |
Positive (Low Yield) |
Highly fundamental, zero reliance on chance |
|
Broad Global Equity Index |
Sound, Diversified Investing |
Long (10 to 30+ Years) |
Positive (Moderate/High) |
Primarily driven by macroeconomic growth5 |
|
Single Blue-Chip Stock |
Concentrated Investing |
Medium to Long |
Positive (High Variance) |
Heavily exposed to idiosyncratic corporate risk1 |
|
Thematic Tech ETFs |
High-Variance Speculation |
Short to Medium |
Positive (Highly Skewed) |
Extreme dependency on specific, localized market narratives4 |
|
0DTE Options / Margin |
Extreme Speculation |
Intra-day (Hours/Minutes) |
Negative (Premium Decay/Fees) |
Dominated entirely by random market noise9 |
|
Roulette / Casino Games |
Pure Gambling |
Instantaneous (Seconds) |
Strictly Negative (- House Edge) |
100% Random Chance, zero fundamentals6 |
|
State Lotteries |
Pure Gambling |
Instantaneous |
Deeply Negative (- 100% long term) |
100% Random Chance, massive wealth destruction5 |
As an individual moves from the top to the bottom of this conceptual spectrum, the statistical variance in potential outcomes widens drastically, the true expected value shifts aggressively from positive to negative, and the primary driver of the eventual outcome transitions away from fundamental economic value creation toward sheer mathematical variance and random chance1.
For instance, investing an entire portfolio into a single, highly volatile corporate equity presents a massive dispersion in potential outcomes. An individual might achieve spectacular, generational wealth if the specific company violently succeeds—such as the documented case of Brandon Smith, who invested his entire net worth into Tesla shares and achieved millionaire status within three years1. However, this individual equally risks total, unrecoverable ruin if the company fails1. While technically categorized as an investment because there is an underlying business entity generating goods, an entirely undiversified single-stock portfolio pushes the participant dangerously close to the gambling threshold, substituting broad economic participation for extreme, localized idiosyncratic risk1.
Systemic Macroeconomic Consequences of Capital Misallocation
The widespread psychological shift from ownership-based, long-term investing to wager-based, hyper-active speculation carries profound implications not just for the individual participant's net worth, but for the fundamental health of the broader macroeconomic system. Investing functions as the critical circulatory system for the allocation of capital to productive, innovative enterprises. When individuals purchase broad equities or corporate bonds, they are indirectly financing technological innovation, global infrastructure development, and corporate expansion. The investor is an active, vital participant in the ongoing enterprise of societal wealth creation2.
Conversely, when vast sums of retail capital are steadily diverted away from broad equity and fixed-income markets and channeled into negative-expected-value speculative platforms, online sportsbooks, or ultra-short-term derivative instruments, that capital is no longer participating in economic formation2. Rigorous industry research highlights that dollars deposited into negative EV betting applications or consumed by derivative premium decay are rarely, if ever, redeployed into equivalent, productive forms of wealth-generating risk-taking2. Instead, that capital is systematically and permanently consumed by the platform's embedded house edge and institutional transaction fees2.
The statistics regarding long-term retail success in these highly speculative environments are deeply sobering. Comprehensive historical data analysis reveals that fewer than 5% of all active participants on online betting and high-frequency speculative applications ever successfully withdraw more money than they deposit2. Flipping this statistic exposes a brutal reality: over 95% of active participants in these ecosystems operate as net losers over time2. This staggering failure rate is not a consequence of unfortunate timing, poor market conditions, or random bad luck; it is the mathematically guaranteed, unavoidable outcome of continuous, sustained participation in a closed systemic loop designed strictly with a negative expected value2.
When a massive demographic subset of retail participants—particularly younger, heavily indebted cohorts—shifts their financial focus from the slow, mathematical accumulation of diversified assets to the rapid, gamified consumption of capital via speculation, the aggregate capability for generational wealth creation is severely compromised. The true societal cost is not merely the sum of the losing bets; it is the staggering loss of decades of compounding interest that would have accrued had that capital been deployed productively into the global market2.
Reclaiming Market Mechanics: Positive Gamification and Education
While the contemporary digital environment has demonstrably enabled the rapid, dangerous gamification of speculative risk, it is critical for industry professionals and regulators to recognize that game-like digital elements are not inherently or exclusively malicious. The exact same neurological drivers that strongly encourage detrimental, high-frequency trading can theoretically be intelligently inverted to heavily promote positive, fundamentally sound long-term financial behaviors8.
Recent industry research and regulatory framework reviews have successfully identified several positive use cases for the strategic deployment of digital gamification. When financial applications utilize goal-setting interfaces, long-term progress tracking metrics, and psychological reward systems to directly incentivize portfolio diversification rather than sheer trading volume, they can actively and measurably enhance long-term investor outcomes8.
For example, a digital platform that specifically rewards a user with visual accolades or increased platform standing for maintaining a strict buy-and-hold strategy through a period of extreme market volatility, or one that visually and interactively tracks the immense compounding power of automated dividend reinvestment over a simulated 30-year horizon, leverages potent behavioral psychology to deeply reinforce sound financial habits8. These positive uses of gamification act as a behavioral counterweight, aligning user interface design with the actual long-term financial well-being of the investor, actively discouraging inappropriately risky behavior and improving general market knowledge8.
However, mechanically mitigating the severe negative impacts of predatory, hedonic gamification requires a massive, concerted effort in foundational financial literacy. Financial institutions, regulatory bodies, and educational non-profits must fiercely focus on teaching retail participants the core, immutable principles of capital markets: the absolute mathematical necessity of broad asset diversification, the vital importance of maintaining emotional discipline throughout highly varied, stressful economic cycles, and the sobering reality of long-term expected returns versus the illusion of rapid wealth2.
Individual-level cognitive mitigation techniques are absolutely essential to preserving decision-making autonomy in an increasingly complex, predatory digital landscape8. Investors must be systematically taught how to recognize the psychological manipulation embedded within points systems, aggressive leaderboards, and the artificial urgency created by expiring derivative contracts8. Only by understanding the precise neurological mechanisms being used against them can retail participants successfully resist the urge to substitute sound investment for rapid speculation.
Conclusion
The distinction between investing and gambling is emphatically not merely a matter of semantic preference, regulatory jargon, or subjective risk tolerance; it represents a fundamental, mathematical divergence in structural architecture, economic utility, and psychological intent. While the highly digitized 2026 marketplace has intentionally and aggressively blurred these lines through the slick gamification of speculative instruments, the underlying realities of these two completely separate activities remain rigorously immutable.
True, sound investing is the slow, deliberate, and mathematically rational commitment of capital to productive global enterprises. It relies entirely on the positive mathematical expectation generated by macro-economic growth, continuous corporate earnings, and the immense power of time-horizon diversification. It transforms the participant into an owner of tangible assets, successfully insulating them from the random, chaotic walk of daily price action through the sheer gravity of long-term compounding.
Conversely, gambling—whether executed overtly on a green felt casino floor or heavily disguised as hyper-active, leveraged day trading on a smartphone application—is strictly participation in an isolated, negative-sum event where the statistical probability is structurally, intentionally designed to consume the participant's capital over time.
Navigating this treacherous dichotomy is paramount for modern financial survival and generational wealth accumulation. As sophisticated digital platforms continue to relentlessly optimize their user interfaces to trigger the specific neurological responses associated with variable, intermittent rewards, market participants must anchor themselves to strict mathematical literacy to navigate their financial choices. True wealth creation ultimately relies on capturing the positive expected value of real capital formation, necessitating a complete, foundational rejection of the highly seductive, psychologically potent, yet mathematically ruinous illusion of the wager.