Ask “what is Chapter 13 bankruptcy known for,” and the answer is its court-confirmed repayment plan. You don’t have to lose your property to reorganize debts and catch up on certain missed payments under that plan. U.S. Courts reports that Chapter 13 made up 38% of consumer bankruptcy filings in 2025.
Is your mortgage payment overdue right now?
What Is Chapter 13 Bankruptcy Known For?
Property protection depends on an active case
With Chapter 13 repayment, you can keep a home or vehicle instead of having it liquidated as nonexempt property. Don’t count on keeping it. You’ll still need to make required current payments while following your plan as the court’s orders require. This is general information, not advice for your case; your circumstances and court proceedings determine whether you qualify and what’s exempt.
Can Chapter 13 pause a South Carolina foreclosure?
When you file, a foreclosure can pause. It’s a temporary pause. U.S. Courts says filing triggers the federal automatic stay, which covers most collection activity, including many foreclosure proceedings. As you catch up on arrears and keep making regular payments, the mortgage lien doesn’t go away. At a creditor’s request, the court can lift the stay, which repeat-filing rules can also limit.
For York County homeowners, it’s still federal court that handles bankruptcy. On exemptions and the timing of any foreclosure sale, you’ll still need advice specific to South Carolina.
How a Chapter 13 Repayment Plan Works
Regular income and disposable income
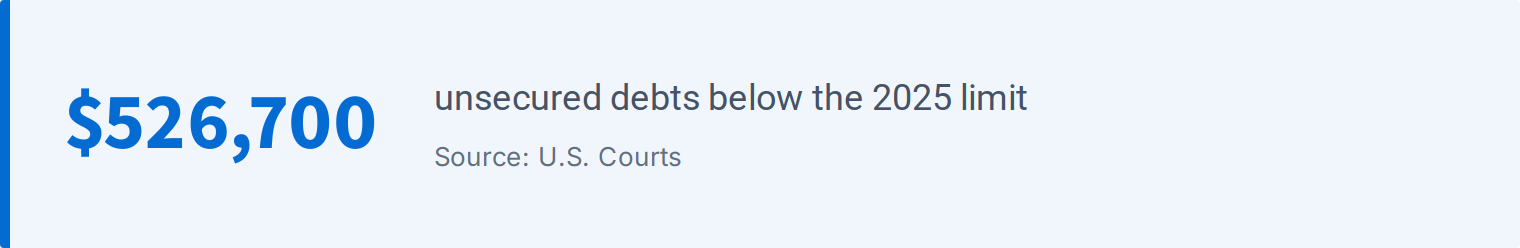
Without regular income and debts below the legal limits, you don’t qualify to use Chapter 13. According to U.S. Courts, in 2025 you need unsecured debts below $526,700 and secured debts below $1,580,125. Don’t expect fixed limits. Your proposed payments depend on disposable income, the money you’ve got left after allowable expenses. You’ll still have bills to pay, so the budget in your plan needs enough money left for them.
The three-to-five-year schedule
U.S. Courts’ Chapter 13 Bankruptcy Basics describes a plan that usually runs for three to five years. Under your confirmed plan, a trustee collects your regular payments first, then passes the money to creditors. Your income, measured against the applicable state median, helps determine how long you’ll have to stay in the plan.
A homeowner who is behind on payments
Picture a homeowner in Rock Hill who’s missed mortgage payments but earns regular wages, enough to start paying the normal monthly amount again. Those arrears can be spread over the proposed plan’s full term, with the homeowner still making the current payments. Nobody can promise that result. After paying for necessities like groceries and utilities, the household must have money left for arrears and current payments.
Chapter 13 and Chapter 7 Take Different Routes
What Chapter 13 bankruptcy is known for, compared with Chapter 7 liquidation, is a court-supervised repayment structure. If you qualify, catching up on missed payments over time doesn’t have to cost you your property.
| Issue | Chapter 13 | Chapter 7 |
|---|---|---|
| Basic process | Court-confirmed repayment plan | Liquidation process handled by a trustee |
| Property | May be retained when plan and payment requirements are met | A trustee may sell nonexempt property, although many cases have no distributable assets |
| Mortgage arrears | May be cured over time while current payments continue | Does not provide a multiyear repayment plan for curing arrears |
| Typical duration | Multiyear plan | Usually shorter, subject to case details |
Not every Chapter 7 debtor has to surrender property. Your applicable exemptions protect equity; check how much before deciding, then compare your likely plan payment with the mortgage arrears you need to catch up on.
What Debts Chapter 13 Can Include
How claims are paid through the plan
Claims fall into three broad categories, says U.S. Courts. Priority claims get special treatment: full payment, with only limited exceptions to that rule. Your car can back a secured claim; paying arrears or continuing installments may be required for that claim. If your plan satisfies confirmation requirements, general unsecured claims may receive only partial payment. One such requirement is that creditors receive at least what Chapter 7 liquidation would give them.
Debts that may survive discharge
Domestic support obligations and certain taxes generally survive an ordinary Chapter 13 discharge, according to U.S. Courts. Most qualifying student loans generally won’t be discharged, either. Long-term mortgage obligations can outlast the end of your plan. A debt in your case isn’t necessarily erased at discharge. Child support left unpaid remains due.
A Repayment Plan Must Be Sustainable
During 2025, 183,808 Chapter 13 consumer cases ended in dismissal or plan completion, according to U.S. Courts’ 2025 BAPCPA report. Of those cases, dismissals numbered 101,709; 82,099 ended in discharge after plan completion, making up 45% of the group. The figures track cases that ended during the reporting year, rather than eventual outcomes for newly filed cases.
Your case can be threatened by missed trustee payments. An unaffordable budget can do the same, as can failing to keep up with required ongoing obligations. Why individual cases were dismissed isn’t established by U.S. Courts’ report. Before you file, compare the proposed payment with several months of your household’s actual expenses.
Practical Questions During and After Chapter 13
How does Chapter 13 affect your credit and daily finances?
Although bankruptcy can affect your access to credit, plan payments also tighten your budget. According to the Consumer Financial Protection Bureau, federal reporting rules allow bankruptcy information to remain on your credit report for up to ten years. While making required payments, you still have to cover ordinary household expenses.
Can you finance a car during a Chapter 13 plan?
Yes, buying a car may still be possible. Before you take on new credit, U.S. Courts advises you to consult the trustee. Court or trustee approval may be necessary, but it isn’t automatic. Be ready to document why the vehicle is necessary and how its loan terms fit beside your plan payment.
When can a hardship discharge apply?
Before a hardship discharge is available, the court must find that you meet the conditions described by U.S. Courts. Circumstances for which you cannot justly be held accountable must prevent you from finishing the plan. The plan must be impractical to modify, with unsecured creditors having received at least what Chapter 7 liquidation would provide. This narrow relief comes only through a court ruling.
Does completing Chapter 13 create a fresh start?
Subject to court requirements, finishing your plan can discharge eligible debts. Some obligations aren’t discharged, U.S. Courts explains, and secured creditors may keep their property rights. A fresh start still doesn’t necessarily mean an erased credit history or a debt-free household. A mortgage lien may still secure money you owe.
How soon can a credit score reach 700?
Neither law nor court rule guarantees a 700 score by any particular date. No scoring model promises one, either. Reporting limits, rather than a guaranteed recovery schedule, are what Consumer Financial Protection Bureau guidance describes. The path your score takes depends on your starting credit file, then later payment history, balances and new credit activity.
Can you keep cell phone service in Chapter 13?
Yes, ordinary cell phone service isn’t prohibited by Chapter 13. But if you finance a handset, U.S. Courts’ warning about new credit applies because the installment agreement can create post-filing debt. Before signing a device installment agreement, check what your plan and trustee require.
Protecting Property Requires a Workable Plan
If your regular income supports a realistic household budget and you follow the confirmed plan, Chapter 13 can give you time to address mortgage arrears. Chapter 13 won’t suit every debtor. Gather your mortgage statements, pay records, tax documents and a current monthly expense ledger before seeking case-specific advice.
Sources
- U.S. Courts: 2025 BAPCPA Report.
- U.S. Courts: Chapter 13 Bankruptcy Basics.
- Consumer Financial Protection Bureau: How long does negative information remain on my credit report?